Gold Holding Limit in India
By Krishna Arya | NetworkBharat.com
Can you legally keep 500 grams, 1 kilogram or even 2 kilograms of gold at home in India? Does the Income Tax Department impose a limit on how much gold jewellery a family can own? And can officials seize gold if you cannot produce old purchase bills?
These are some of the most frequently asked questions among Indian households, particularly during weddings, festivals and family inheritance.
The answer may surprise you: India does not prescribe a fixed maximum limit on owning gold jewellery if its source is properly explained. However, the Central Board of Direct Taxes (CBDT) has issued guidelines specifying quantities of jewellery that should ordinarily not be seized during an Income Tax search.
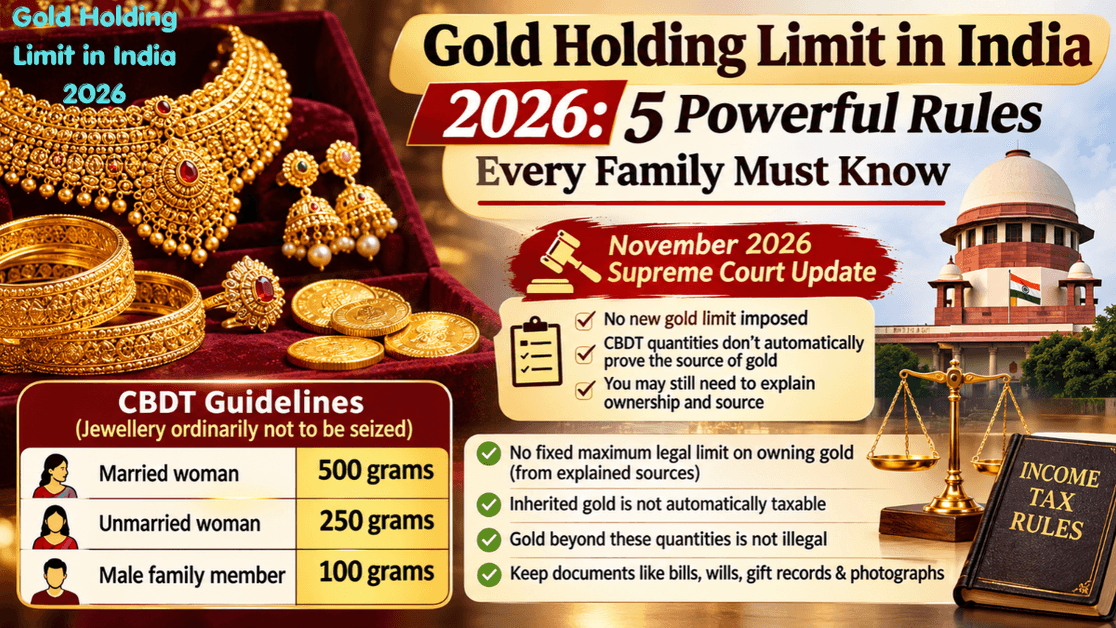
According to CBDT Instruction No. 1916 dated 11 May 1994, these quantities are 500 grams for a married woman, 250 grams for an unmarried woman and 100 grams for a male family member.
A significant legal development in November 2026 has also brought renewed attention to these rules. The Supreme Court has clarified that merely possessing gold within these quantities does not automatically establish the legitimate source of the jewellery.
Here is a detailed explanation of the Gold Holding Limit in India, the latest legal position, Income Tax rules, practical examples and precautions every family should understand.
Gold Holding Limit in India 2026: What Is the Legal Limit?
There is no fixed statutory ceiling on the quantity of gold jewellery an individual can legally own in India, provided the person can satisfactorily explain its source of acquisition.
The Government of India clarified this position through a Press Information Bureau release dated 1 December 2016.
The clarification stated that there is no limit on holding gold jewellery or ornaments if they have been acquired from explained sources of income, including inheritance.
However, the government also referred to the existing CBDT guidelines on jewellery seizure during Income Tax searches.
This means that the commonly quoted 500-gram, 250-gram and 100-gram figures are not maximum ownership limits. They are administrative guidelines for Income Tax search authorities.
Gold Holding Limit in India: CBDT Rules Explained
CBDT Instruction No. 1916, issued on 11 May 1994, provides guidance on the quantity of jewellery that should ordinarily not be seized during a search operation.
The prescribed quantities are:
| Category of family member | Gold jewellery ordinarily not to be seized |
|---|---|
| Married woman | 500 grams |
| Unmarried woman | 250 grams |
| Male family member | 100 grams |
These quantities are particularly relevant when an Income Tax search takes place and the authorities discover gold jewellery in a household.
Important: These are not separate tax-free allowances or ownership ceilings. Possessing more gold does not automatically make the additional quantity illegal or taxable.
The CBDT instruction also gives authorised officers discretion to exclude a larger quantity of jewellery from seizure after considering the family’s social status, customs, traditions and other circumstances.
Five Important Gold Rules Every Indian Household Should Know
1. Married Women Can Have 500 Grams of Gold Protected From Ordinary Seizure
Under the CBDT guidelines, jewellery weighing up to 500 grams in the possession of a married woman should ordinarily not be seized during an Income Tax search.
This recognises the Indian tradition of receiving gold jewellery during marriage and other family occasions.
2. Unmarried Women Have a 250-Gram Seizure Guideline
The prescribed quantity for an unmarried woman is 250 grams.
Gold received through family gifts, festivals and other customary occasions may form part of her jewellery holdings.
3. Male Family Members Have a 100-Gram Guideline
The CBDT instruction also recognises jewellery held by male members of a family.
The quantity ordinarily not to be seized is 100 grams per male family member.
4. Inherited Gold Does Not Automatically Become Taxable
Gold jewellery inherited from parents, grandparents or other relatives is not automatically taxable merely because the recipient did not purchase it personally.
However, a person may need to establish the inheritance and ownership when questioned by tax authorities.
Useful supporting records include wills, succession documents, family settlement papers, old photographs and other credible evidence.
5. Gold Beyond These Quantities Is Not Automatically Illegal
This is perhaps the most misunderstood aspect of Indian gold regulations.
A family possessing 800 grams, 1 kilogram or even more jewellery is not automatically violating the law.
The authorities may examine the source of acquisition, the family’s financial position, ownership, gifts, inheritance and other available evidence.
The CBDT guidelines also allow search officers to consider family customs and circumstances while deciding whether additional jewellery should be seized.
Gold Holding Limit in India: Detailed Practical Examples
Understanding the rules through examples makes the legal position easier to understand.
Example 1: A Married Woman Has 450 Grams of Gold
Suppose a married woman has 450 grams of gold jewellery received during her wedding and through family gifts.
This quantity falls within the 500-gram CBDT guideline.
Ordinarily, this jewellery should not be seized during an Income Tax search under the instruction.
Example 2: A Married Woman Has 750 Grams of Gold
Suppose a married woman possesses 750 grams of jewellery.
The additional 250 grams does not automatically become illegal or unexplained income.
Authorities may examine the source of the additional jewellery, including wedding gifts, inheritance, past purchases and family circumstances.
Example 3: A Family Has 1.5 Kilograms of Gold
Consider a household with:
- Married woman: 700 grams
- Unmarried daughter: 300 grams
- Husband: 200 grams
- Total family jewellery: 1,200 grams
The combined quantities under the CBDT guidelines would be 800 grams.
However, the remaining 400 grams cannot automatically be treated as illegal or unexplained gold.
The authorities must consider the relevant facts, including ownership, financial background and the source of acquisition.
Example 4: A Woman Has Inherited Gold Without Old Purchase Bills
Suppose a woman inherits jewellery from her grandmother, but the original purchase receipts are unavailable.
The absence of old bills does not automatically make inherited jewellery illegal.
She may support her explanation through family records, photographs, inheritance documents, affidavits and other credible evidence.
A consistent explanation of the source and ownership is important.
November 2026 Supreme Court Development: Why Gold Ownership Rules Are in the News
A significant development concerning gold ownership and unexplained assets emerged in November 2026.
In the case of State of Bihar vs Phulpari Kumari, the Supreme Court passed an order dated 2 November 2026, setting aside a Patna High Court order that had quashed criminal proceedings in a disproportionate-assets case.
The matter attracted attention because the High Court had relied on CBDT guidelines concerning permissible quantities of gold jewellery.
According to the legal reporting on the Supreme Court order, the Court clarified that merely relying on the CBDT quantities of 500 grams, 250 grams and 100 grams does not, by itself, establish that the source of the jewellery has been satisfactorily explained.
What Does the Supreme Court Development Mean?
The important distinction is between two separate issues:
- Protection against seizure: CBDT guidelines provide quantities of jewellery that should ordinarily not be seized during an Income Tax search.
- Explanation of ownership and source: When authorities legally question the source of an asset, the prescribed quantities do not automatically establish how that asset was acquired.
In other words, staying within the CBDT quantities does not create an automatic exemption from explaining the source of gold in every legal proceeding.
Does the Supreme Court Order Introduce a New Gold Limit?
No.
The November 2026 order does not introduce a new maximum gold ownership limit for Indian households.
It does not cancel the 1994 CBDT instruction or establish a compulsory requirement to retain purchase bills for every piece of ancestral jewellery.
Instead, it highlights that the CBDT seizure guidelines and the obligation to explain the source of assets are two different legal questions.
Families should therefore preserve available evidence of significant gold holdings, particularly jewellery received through inheritance and family transfers.
Can the Income Tax Department Seize Gold Above 500 Grams?
Yes, jewellery exceeding the CBDT guideline quantities may be examined and, depending on the circumstances and applicable law, may be seized.
However, exceeding the prescribed quantities does not automatically make the additional jewellery unexplained income.
The authorised officer must consider the circumstances, the source of acquisition and relevant evidence.
The CBDT instruction also allows officers to exclude a larger quantity from seizure after considering the family’s status, traditions and other circumstances.
The Income Tax Department’s Search and Seizure Manual 2025 also explains that the source and nature of possession should be examined before deciding whether jewellery should be seized.
What Happens If You Cannot Produce Gold Purchase Bills?
Many Indian households have jewellery purchased decades ago. Some pieces may have been received during weddings or inherited from previous generations.
Consequently, it may not always be possible to produce original purchase receipts.
However, the absence of an invoice does not automatically mean that the jewellery is illegal.
Other supporting evidence may help establish ownership and the source of acquisition.
These may include:
- Wedding photographs showing jewellery received during marriage.
- Gift declarations or family gift records.
- Inheritance documents and wills.
- Bank locker records.
- Previous Income Tax Returns.
- Jewellery valuation certificates.
- Family settlement documents.
- Affidavits and other credible supporting evidence.
No single document guarantees acceptance in every case. Authorities may examine the overall circumstances and consistency of the explanation.
Documents Families Should Keep to Support Gold Ownership
| Document | Why it is useful |
|---|---|
| Purchase bills | Establishes purchase details and value |
| Wedding photographs | Supports the history of wedding jewellery |
| Gift records | Helps establish jewellery received as gifts |
| Will or succession documents | Supports inheritance claims |
| Valuation certificate | Records weight, purity and estimated value |
| Bank locker records | Helps establish possession and storage history |
| Income Tax Returns | May support the family’s financial background |
| Family settlement papers | Helps establish ownership distribution |
Families should maintain an item-wise inventory of significant jewellery, with photographs, approximate purchase dates, weight and ownership details.
This can be particularly useful when jewellery is transferred between generations or kept at a common family residence.
Is Gold Inherited From Parents Taxable in India?
Gold inherited from parents or grandparents is not automatically taxable merely because it has been inherited.
The Government’s 2016 clarification specifically recognised inheritance as an explained source of gold jewellery.
However, tax implications may arise when inherited jewellery is subsequently sold.
The tax treatment of a sale depends on the applicable capital gains provisions, acquisition cost rules and holding period.
Therefore, inheritance and sale are two different tax events and should not be confused.
Important Income Tax Provisions Relating to Unexplained Gold
Gold jewellery may become a tax issue if authorities find that its source cannot be satisfactorily explained.
There is also an important change in India’s income-tax legislation in 2026.
The Income-tax Act, 2025 came into effect on 1 April 2026. For relevant transactions and proceedings under the new legislation, Section 104 deals with unexplained assets.
The earlier Income-tax Act, 1961 contained Section 69A, which dealt with unexplained money and other valuable assets, including jewellery.
The applicable provision depends on the relevant assessment period and legal circumstances.
Taxpayers should not assume that an unexplained asset will be treated as tax-free simply because its weight falls within the CBDT guidelines.
Gold Holding Limit in India 2026: Key Takeaways
| Question | Correct position |
|---|---|
| Is there a maximum legal gold ownership limit? | No fixed maximum for jewellery from explained sources |
| Married woman’s CBDT guideline | 500 grams |
| Unmarried woman’s CBDT guideline | 250 grams |
| Male family member’s CBDT guideline | 100 grams |
| Is gold above these quantities illegal? | No, not automatically |
| Is inherited gold automatically taxable? | No |
| Are purchase bills compulsory for every old jewellery item? | No blanket requirement |
| Can authorities examine the source of gold? | Yes |
| Did the November 2026 Supreme Court order introduce a new limit? | No |
FAQs
1. How much gold can a married woman legally keep at home in India?
There is no fixed maximum ownership limit if the source of the gold is explained. The CBDT guideline provides that 500 grams of jewellery in the possession of a married woman should ordinarily not be seized during an Income Tax search.
2. Can an unmarried woman keep 500 grams of gold?
Yes. The 250-gram quantity is a CBDT seizure guideline, not a legal maximum ownership limit. A woman may legitimately own more gold if its source is explained.
3. How much gold can a man keep at home in India?
The CBDT guideline specifies 100 grams of jewellery per male family member as the quantity that should ordinarily not be seized. It is not a maximum ownership limit.
4. Can the Income Tax Department seize gold above 500 grams?
Jewellery above the prescribed quantities may be examined and may be seized depending on the circumstances. However, exceeding 500 grams does not automatically establish undisclosed income.
5. Is gold received at a wedding taxable?
Gold received as a genuine wedding gift is generally covered by the tax provisions relating to gifts received on the occasion of marriage. Proper evidence of the occasion and source can be useful.
6. Is inherited gold taxable in India?
Inheritance itself is not generally treated as taxable income in the hands of the recipient. However, a person may need to establish the source and ownership if questioned by authorities.
7. Can I keep gold without purchase bills?
The absence of old purchase bills does not automatically make jewellery illegal. Other evidence, such as inheritance records, photographs, gift records and financial history, may support the explanation.
8. Did the Supreme Court change the gold holding limit in November 2026?
No. The Supreme Court development in State of Bihar vs Phulpari Kumari concerned the evidentiary significance of CBDT gold seizure guidelines. It did not introduce a new maximum gold ownership limit.
9. Does the 500-gram rule apply to gold coins and bars?
CBDT Instruction No. 1916 specifically addresses gold jewellery and ornaments. Its quantities should not automatically be treated as a blanket safe-harbour limit for gold bars, bullion or coins.
10. What should families do to protect their gold ownership records?
Maintain purchase invoices where available, photographs, inheritance documents, gift records, valuation reports and a clear inventory identifying the owners of significant jewellery holdings.
Conclusion: Understand the Difference Between Gold Ownership and Tax Rules
The Gold Holding Limit in India is often misunderstood because the CBDT’s 500-gram, 250-gram and 100-gram guidelines are frequently presented as maximum legal ownership limits.
That interpretation is incorrect.
The government has clarified that individuals can own gold jewellery beyond these quantities when its source is properly explained. The CBDT guidelines primarily protect specified quantities from ordinary seizure during Income Tax searches.
The November 2026 Supreme Court development reinforces another important principle: the quantity of gold alone does not establish the source of an asset.
For Indian families, the practical lesson is simple: preserve available records, document significant inheritance and family transfers, and maintain a clear inventory of jewellery.
Gold is not merely an investment in India; it is also part of family traditions and inheritance. Understanding the law can help families protect both their assets and their peace of mind.
#GoldHoldingLimit, #GoldRules2026, #GoldInIndia, #IncomeTaxRules, #CBDT, #GoldJewellery, #GoldInvestment, #TaxRulesIndia, #GoldOwnership, #PersonalFinance, #IndianTaxLaws, #GoldNews
Disclaimer: This article is intended for general information and educational purposes. It is not legal or tax advice. Tax treatment and search-related decisions depend on the applicable law, facts and evidence of each case. Consult a qualified chartered accountant or tax lawyer for individual advice.
Published by: NetworkBharat.com | Author: Krishna Arya
Official and authoritative external references
Use these sources in your article to strengthen its credibility: